HVAC contractor financing in Corona, CA lets homeowners spread the cost of a new system over monthly payments instead of paying the full price upfront. With triple-digit summer heat and a mix of aging and new homes across Corona, a financing plan can be the difference between replacing a failing system now or limping through another season on a repair. This guide breaks down the real financing structures, credit requirements, and one 2026 change that affects every HVAC buyer's bottom line.
Financing Options for HVAC Installation in Corona, CA
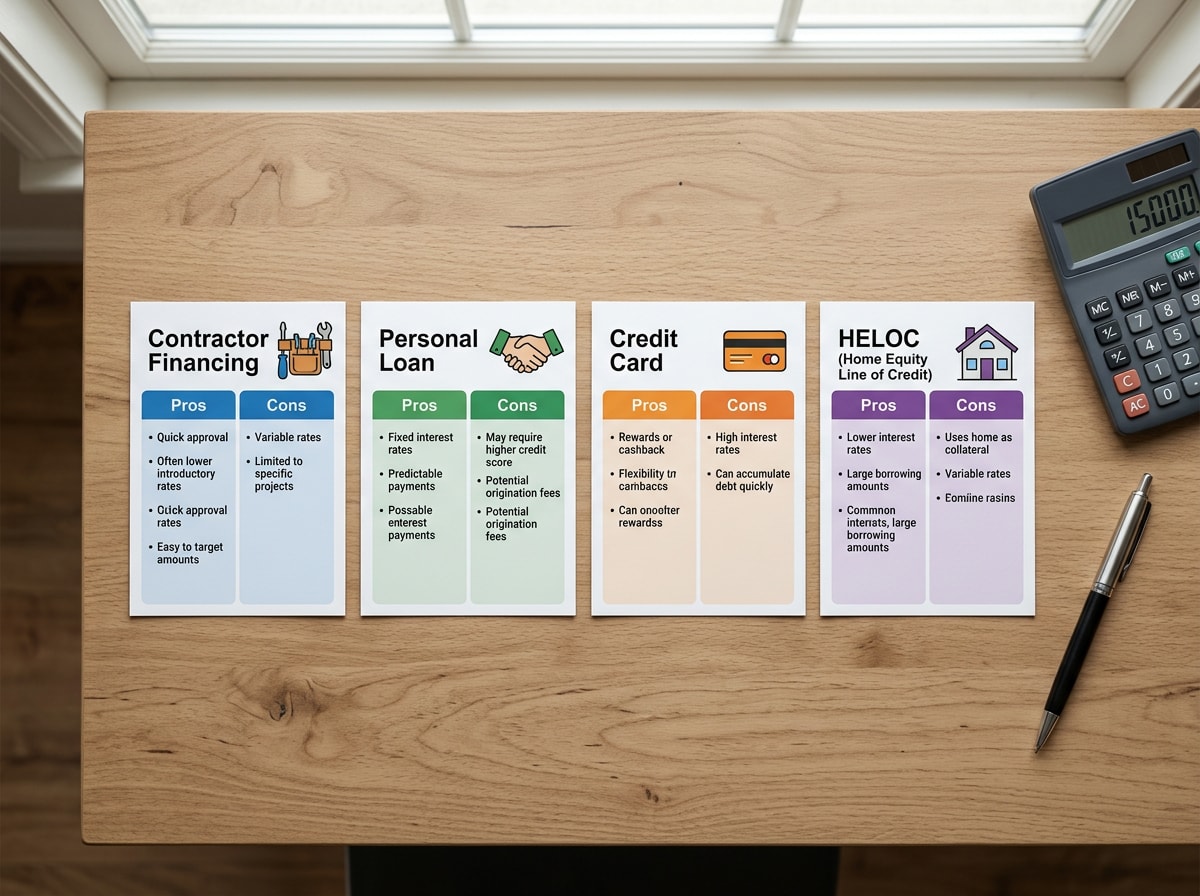
Most Corona homeowners choose between four financing paths when a system needs to be replaced. Each works differently depending on your credit profile, timeline, and how much equity you have in your home.
| Option | How it works | Best for |
|---|---|---|
| Contractor promotional financing | Approval tied directly to the installation; often advertised as 0% interest for qualified buyers | Buyers who want fast approval during the estimate |
| Personal loan | Fixed monthly payment through a bank or credit union; interest accrues immediately | Buyers who want funds outside the contractor relationship |
| 0% APR credit card | Interest-free only if paid off within the promotional window | Smaller jobs or buyers confident they can pay it off fast |
| HELOC | Lower rates for homeowners with equity; slower approval process | Larger projects where rate matters more than speed |
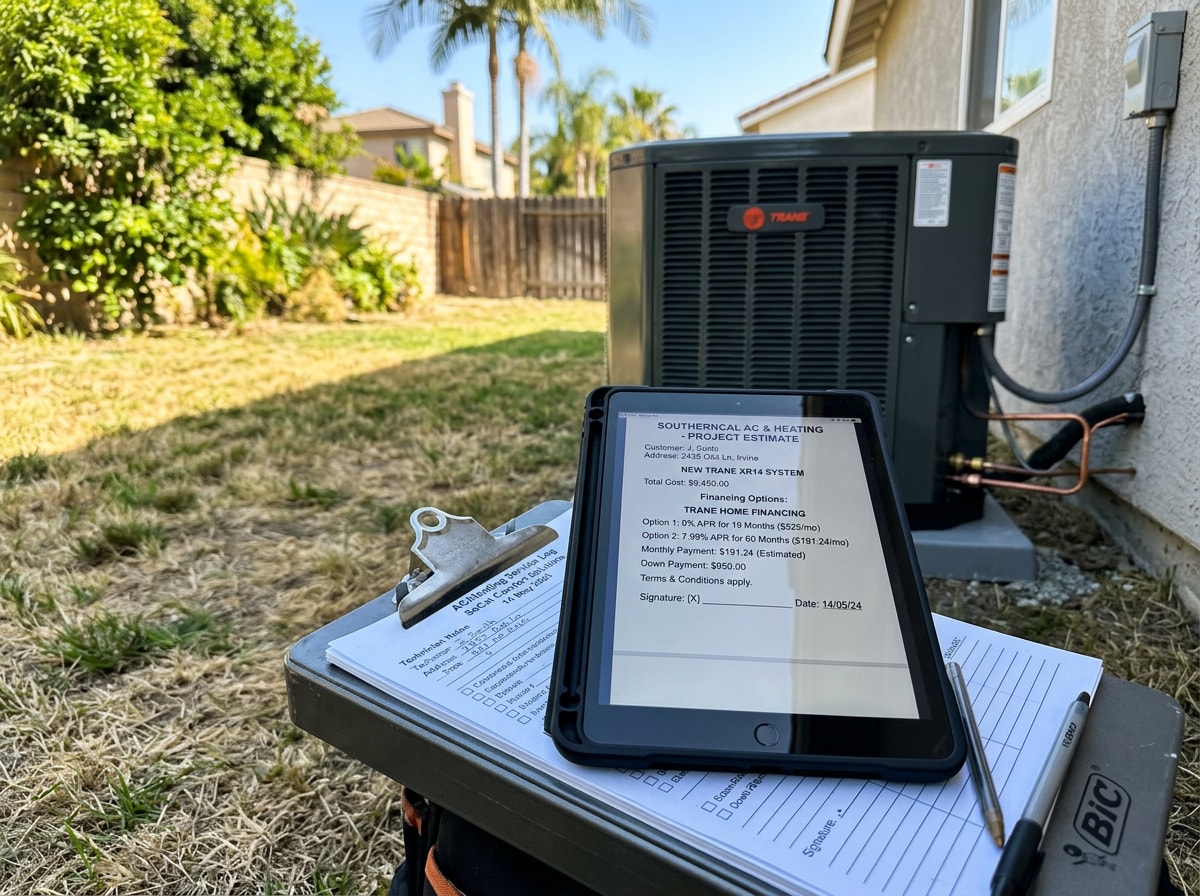
Contractor-arranged financing is usually the fastest path because approval happens during your estimate rather than through a separate loan application. Our team can walk you through current promotional terms and what you'd qualify for before any work is scheduled.
What Changed for 2026: The Federal Tax Credit Is Gone
This is the part most financing guides skip, and it matters if you're budgeting a 2026 installation. The Energy Efficient Home Improvement Credit (Section 25C), which used to knock up to $2,000 off a qualifying heat pump or $600 off a high-efficiency air conditioner, no longer applies to equipment installed this year. The credit will not be allowed for any property placed in service after December 31, 2025. The same deadline ended the related Residential Clean Energy Credit for other home energy upgrades.
Practically, that means the federal discount you may have read about in older articles or seen a contractor mention isn't part of your 2026 math anymore. Financing fills that gap for most Corona households now. If a contractor's quote still references a federal tax credit for a system installed in 2026, that's outdated information worth double-checking before you sign anything.
Credit Score Requirements for HVAC Financing
Lenders pull your credit score to estimate repayment risk, and many scores range from 300 to 850, but different companies use different ranges . There isn't one universal cutoff for HVAC financing since every lender and promotion sets its own minimum.
Here's generally how it breaks down:
- Top-tier promotional offers (0% interest): Reserved for the strongest credit profiles; these promotions are the most competitive, so lenders typically approve only the highest-scoring applicants.
- Standard contractor financing: Covers a wider range of credit profiles with adjusted rates based on risk.
- Fair or limited credit: Still has paths to approval, usually with a higher rate or a co-signer, rather than automatic denial.
Your score is only part of the picture. Income, existing debt, and payment history all factor into what a lender offers you.
Can You Get HVAC Financing With Bad Credit?
Yes, in most cases. A lower credit score doesn't automatically disqualify you from financing; it usually changes the terms rather than closing the door entirely. Options include:
- Co-signer applications – a creditworthy co-signer can unlock standard rates even if your own score is limited.
- Contractor-arranged alternative financing – some lenders specialize in working with buyers outside the top credit tiers.
- Smaller system financing or staged repairs – spreading a larger project into phases can reduce the loan amount needed.
Before signing any agreement, confirm the full APR, the length of the term, and whether the rate is fixed or adjusts after a promotional period. California's Department of Financial Protection and Innovation publishes consumer guidance on credit and credit reports that's worth a quick read before you commit to any loan.
Limited-Time Financing Offers & Discounts for Corona Homeowners
Many HVAC financing promotions in Corona are structured as 12 to 36 months at 0% interest, sometimes with no payments due for the first 90 days. These offers typically apply to full system installs rather than single-component repairs, and they're often stackable with seasonal or loyalty discounts a contractor runs independently.
Ask specifically whether:
- The 0% rate applies for the full term or only an introductory period.
- There's a deferred-interest clause that charges back interest if the balance isn't paid in full by the deadline.
- The promotion can be combined with any other current discount.
Credit Score Basics Worth Understanding Before You Apply
Knowing how your score is built helps you understand why one lender approves you and another doesn't. The several variables affect your credit score, including how many credit accounts you have and how close you are to your credit limit . The Consumer Financial Protection Bureau has a straightforward breakdown of how credit scores are calculated if you want to check where you stand before requesting financing.
In our experience quoting installations across Corona, we show homeowners the cash price and the financed monthly payment side by side on every estimate, so the decision isn't made blind. That transparency tends to matter more to buyers than the headline interest rate alone.
Why Work With a Local Corona HVAC Contractor on Financing
A local HVAC contractor typically handles financing paperwork directly during your estimate rather than routing you through a separate national call center. That means faster answers on approval status, scheduling, and what's actually included in the install, since the person quoting your job is also coordinating the work. For homeowners comparing a local company against a larger chain, that direct line between the estimate, the financing application, and the install crew is usually the biggest practical difference.
Service Areas Near Corona, CA
We install and finance HVAC systems throughout Corona, CA and the surrounding Riverside County communities. If your address falls within our coverage area, financing approval and installation scheduling both move on the same timeline. Browse our full HVAC contractor services to see what's typically included in a financed installation, from air conditioning installation and air conditioning replacement to heating installation.
If you've already compared system costs for a nearby city, our HVAC AC installation cost and permit guide for Murrieta walks through similar pricing factors that apply across the Inland Empire. For details on membership and maintenance pricing specific to Corona, see our HVAC membership guide.
Ready to see your actual numbers? Request a free estimate and we'll show you the cash price and financed payment together, with no pressure either way. You can also start from our homepage to see the full range of services we offer across Corona.
FAQ
Do you offer financing for HVAC installations in Corona, CA?
Yes. Qualified buyers can finance a new system install rather than paying the full cost upfront, subject to lender approval. Ask about current promotional terms when you request your estimate.
What credit score do you need for HVAC financing?
There's no single required score; it depends on the lender and the specific promotion. The best 0% offers go to the strongest credit profiles, while standard financing covers a much wider range. Checking your own score beforehand, using a free resource like the one from the Consumer Financial Protection Bureau, helps you know what to expect before you apply.
Can you get HVAC financing with bad credit?
Yes, in many cases. A lower score usually means a higher rate or the need for a co-signer rather than an automatic denial. Terms will differ from a 0% promotional offer, but approval is often still possible.
Is there still a federal tax credit for HVAC systems installed in 2026?
No. The federal Energy Efficient Home Improvement Credit (Section 25C) ended for any equipment placed in service after December 31, 2025. If a quote or ad still references this credit for a 2026 installation, that information is out of date.
How long are typical HVAC financing terms?
Promotional plans commonly run 12 to 36 months at 0% interest, though longer-term plans with interest are also available for larger installations. Terms vary by lender and the total project cost.
Does financing require a down payment?
Not always. Some contractor-arranged plans offer $0 down for qualified buyers, while others may require a down payment depending on your credit profile and the lender's terms. Ask for the specific requirement during your estimate.
Why should I choose a local Corona HVAC company instead of a national chain?
A local contractor typically handles your estimate, financing application, and installation scheduling through the same team, which usually means faster answers and fewer handoffs compared to a larger, centralized operation.